


What matters to you in 30 seconds
-
Technology shares fell sharply after the US midterms as investors reassessed the outlook for AI infrastructure, with semiconductor shares down almost 9% between 2 and 6 November.
-
Greater scrutiny of data centres could slow development, but scarcer power and computing capacity could also strengthen the position of companies that already have access to them.
-
We remain positive on the long-term AI opportunity. Recent falls have improved valuations in some high-quality technology companies, although a more concentrated market and less supportive interest-rate backdrop call for greater selectivity.
Chart of the week: Market moves since the US midterms
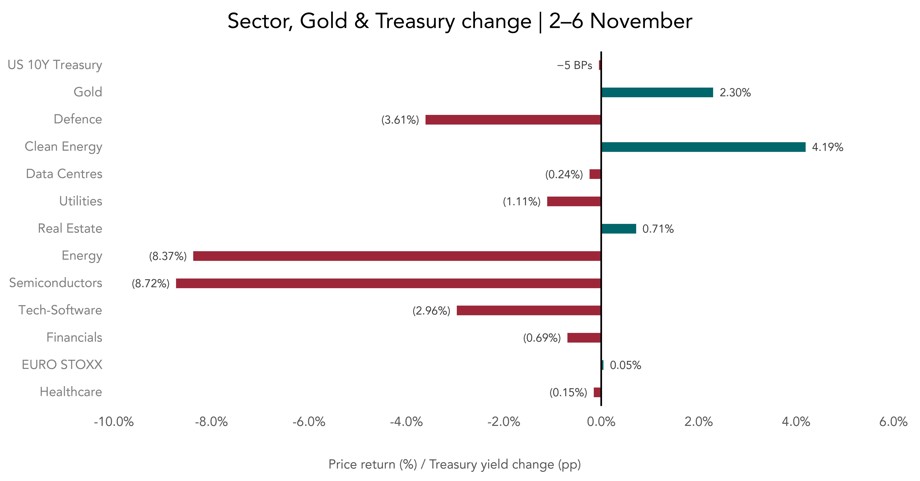
Source: In-house research, LSEG Datastream. Performance from 2 November to 6 November 2026. Key Sector ETFs are used for segment proxies. Past performance is not a reliable indicator of future returns.
A revealing market reaction
The market reaction to the US midterms revealed some clear winners and losers. Between 2 and 6 November, semiconductor shares fell almost 9%, while energy and software stocks also declined. Clean-energy shares gained around 4%, and gold rose more than 2%.
Some of those moves reflected the new balance of power in Washington. The Democratic ‘Blue Sweep’ makes major changes to taxation, spending and regulation harder to pass, along with another significant fiscal expansion. But one of the sharpest moves came from an issue much closer to the heart of the recent equity rally: AI.
Attention has now shifted to the infrastructure behind AI. Greater scrutiny of data-centre development, particularly around power and permits, could delay projects and slow the pace at which new AI infrastructure is built. The reaction quickly spread beyond US technology shares, with Asian semiconductor companies also falling sharply.
This came after a period in which technology companies have accounted for an increasing share of market returns. The concentration had become particularly noticeable in emerging markets, where a relatively small number of Asian technology companies were responsible for a growing proportion of performance.
That concentration was already something we had been addressing in portfolios. Emerging markets had initially provided diversification from the US-led AI theme, but that changed as returns became more dependent on a relatively small group of Asian technology companies. Having benefited from our emerging-market overweight, we took some profit and returned to neutral.
Scarcity could reshape the opportunity
The falls in technology shares do not change our long-term view of AI. There could be more friction around the development of data centres. But if access to power, data-centre capacity and computing infrastructure becomes harder to secure, companies that already have access to them could find themselves in a stronger position.
The sell-off has also improved valuations in parts of the technology sector. Some high-quality businesses are now trading at lower prices even though their earnings prospects remain robust. Alongside the growing importance of access to scarce infrastructure, that leaves us looking more closely at where opportunities within AI may be shifting.
A resilient economy complicates the rate outlook
The election dominated the headlines last week, but economic growth, inflation, interest rates and company earnings are likely to have greater influence over where markets go from here.
The US added 165,000 jobs in October, around 100,000 more than expected. Unemployment edged down to 4.1%, while employment growth in previous months was revised higher. That resilience leaves the US Federal Reserve (Fed) with little reason to cut interest rates in the near term.
Inflation is creating similar constraints in Europe. Euro-area headline inflation rose from 3.8% to 4.0%, its highest level in three years, while core inflation remained elevated at 2.5%. The Bank of England (BoE) also delivered its first rate increase in three years.
For investors, stronger economic activity is clearly preferable to weaker growth. But when growth is holding up and inflation remains elevated, central banks have less reason to lower interest rates. That means markets may have less support from falling rates if company earnings disappoint.
This week
Will the reassessment continue?
Last week was about investors reassessing some of the assumptions that had supported markets. This week should provide more evidence on whether that adjustment has further to run.
US consumer-price data on Tuesday will be the first test, followed by producer prices on Friday. After October's stronger-than-expected employment report, another firm inflation reading would give the Fed even less reason to ease policy. UK third-quarter GDP is also due following the Bank of England's latest rate increase, while Chinese inflation figures should offer a further indication of the strength of domestic demand.
For the AI story, company results may be more revealing. CoreWeave, Cisco and semiconductor-equipment manufacturer Applied Materials are due to report. After last week's sell-off, we will be listening closely to what they say about AI infrastructure demand, data-centre spending and whether corporate investment plans remain intact.