


What matters to you in 30 seconds
-
Bonds are becoming more interesting. Higher yields mean investors can once again earn meaningful income from high-quality bonds.
-
We remain positive on growth, but more selective on risk. Equity markets have stayed resilient despite higher interest rates, but we have added downside protection in eligible portfolios.
-
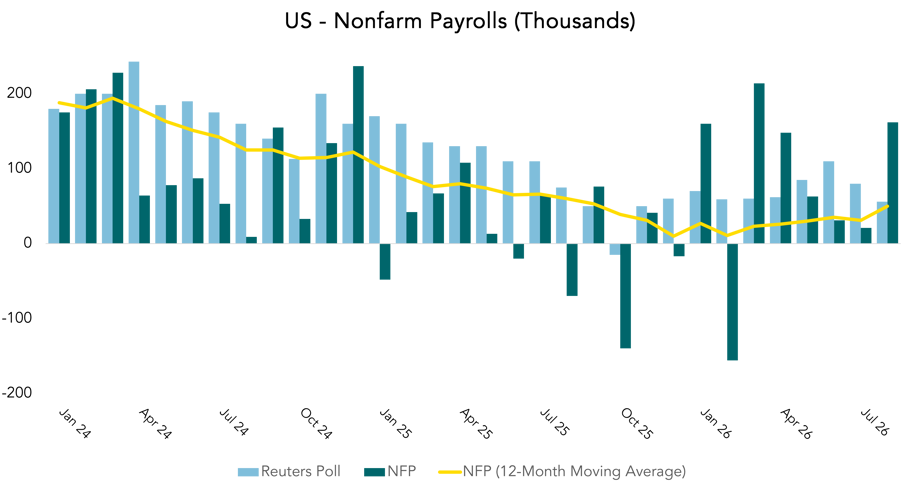
Friday’s US jobs report could be the week’s key market event. Strong nonfarm payrolls data would reinforce expectations for another interest rate hike, while weaker figures could ease pressure on the US Federal Reserve (Fed).
Chart of the week
Source: In-house research, LSEG Datastream
Bonds
Income is back
For years, investors had to accept very little income from high-quality bonds. That environment is changing.
Government bond yields rose again last week across developed markets. Stronger-than-expected economic data and inflation fears prompted investors to reassess the likelihood of further interest rate increases. Fiscal concerns have also contributed to upward pressure on yields. Another, less obvious factor may be the huge investment being directed towards AI infrastructure, which is increasing competition for capital.
Yet focusing on last week’s market move risks missing the bigger story. Bond yields have largely returned to levels that are much closer to long-term historical averages. In many ways, today’s environment looks more normal than the unusually low-rate period that followed the Global Financial Crisis and the Covid shock.
For investors, this matters. Higher yields increase the income available from holding bonds and provide a larger buffer against future market moves. That cushion is now meaningful. Based on our analysis, the yield on the 10-year US Treasury would need to rise to roughly 5.7% over the next year, or around 6.6% over the next two years, before total returns turned negative.
Short-term volatility is still possible. Policy uncertainty, energy prices and competition from strong equity returns could continue to pressure bond markets. Even so, bonds are increasingly able to perform the role investors traditionally expected of them: generating income while contributing to portfolio diversification.
Portfolios
Optimistic, but not complacent
Financial markets continue to adapt to a world of higher interest rates. At the same time, geopolitical tensions and uncertainty in energy markets have increased concerns that inflation may prove more persistent than many expected.
Historically, periods of sharply rising bond yields have often unsettled financial markets. So far, 2026 has been different. Despite higher borrowing costs, equity markets have remained resilient.
One reason may be the powerful investment cycle taking place in AI. Combined with increased spending on energy infrastructure and defence, it has helped support economic activity and investor confidence.
Against that backdrop, we remain moderately overweight equities, yet selective. We continue to favour US and emerging market equities, where growth prospects remain relatively attractive.
That said, strong market performance this year means there is less room for disappointment. For that reason, we have recently increased downside protection within portfolios where regulation and client circumstances permit. Our objective is not to reduce our participation in growth, but to improve resilience should markets become more volatile.
We also remain overweight gold. Growing concerns about debt sustainability across major economies have reinforced its appeal for some investors. Gold may also provide diversification benefits during periods of economic weakness, although its price can be volatile.
Our overall message has not changed. We believe economic growth remains positive, but we see value in balancing participation in that growth with protection against unexpected shocks.
Geopolitics
US-China: less tensions, not a resolution
The relationship between the US and China appeared somewhat more stable last week.
The meeting between Presidents Xi Jinping and Donald Trump generated considerable attention but produced few major policy announcements. More important for markets was the decision to extend last year’s trade truce by two months, keeping tariffs at lower levels until 10 January.
The extension was shorter than many officials had previously suggested. Even so, it gives both sides additional time to pursue a broader agreement and reduces some immediate risks for global markets.
Investors should be careful not to confuse stabilisation with resolution. Strategic competition in areas such as technology, trade and national security remains firmly in place.
Attention will now shift back towards domestic developments.
In China, investors will watch for further signals from policymakers on measures designed to support consumption, housing and economic growth. The challenge remains clear: production continues to outpace consumption, increasing pressure on policymakers to stimulate domestic demand.
In the US, focus is gradually turning towards the approaching midterm elections. Our base case remains a divided Congress, with Democrats regaining control of at least one chamber. While the election result itself matters, investors will be more interested in what it implies for future policy and spending plans.
This week
Can the economy stay strong without reigniting inflation?
The key question for investors this week is whether economic growth remains strong enough to support corporate earnings without creating renewed inflation pressures.
In Europe, inflation data from Spain, France, Italy and Germany will culminate in the Eurozone reading on Friday. With oil prices remaining around USD 100 per barrel, headline inflation is expected to stay elevated.
Markets currently expect the European Central Bank to raise interest rates again. While there is a risk that the central bank does increase rates slightly more, we don’t expect a series of hikes. Higher energy prices reduce consumers’ spending power and may eventually weaken demand, which could allow policymakers to remain on hold.
In the US, attention will focus on the Fed’s preferred measure of inflation, the core personal consumption expenditures index, alongside a series of labour-market indicators including job openings, private payrolls and Friday’s non-farm payrolls report.
Last month’s employment data was strong. If this week’s figures tell a similar story, investors may become more confident that the Fed has one further rate increase ahead. That remains our base case, potentially at either the October or December meeting.
China will also remain in focus. Business surveys released during the week will provide another indication of the balance between production and domestic demand. Investors will look for signs that policymakers may be prepared to accelerate support measures ahead of the Central Committee plenum in late October.